Tuesday, January 01, 2019

Letter To Shareholders (13) - Performance Review 2018Q4

As usual, the Q4 review will be shorter in preparation of the Annual Report.

Economy Commentary
Singapore market and essentially the world markets all face severe pressure in the past months, mainly from Fed interest hikes, trade war and geopolitical risks. STI went down 6.6% YTD, and world indices dropped 9%.

In local markets, we saw the implosion of Asian Pay TV Trust (risk of blindly chasing yield without consideration of sustainability), value destructing rights issue from KBS UBS REIT (stock price fall to rights issue price, highlighting the importance of good management) and Lippo Malls (risk of foreign REITs).


Performance Review Highlights
A falling tide sinks all boats, and our portfolio was not spared. The crash of Kimly was a massive blow to our performance and taught us valuable lessons. YTD, our portfolio is down almost 10.2%. The absolute figure is much more terrifying compared to the correction back in 2015 when our asset size were much smaller.

Lessons Learnt:
We knew Kimly was a speculative position (but still based on fundamentals) right from the start, and we made money initially. Instead of cutting losses after the tide turned, we stupidly held on. 
Cut your losses as soon as you are proven wrong. Don't 心存侥幸 and "hope", especially for such a substantial position.


Evaluating What To Do Now:
While the investigation was unfortunate, Kimly fundamentals actually did not change at all. They are still basically debt free, sitting on mountains ($70m) of cash and still very much profitable (slow growth). The criminal case will no doubt be a huge hangover on the stock price. With with same business, 30% lower price, and no indication of something serious like dishonest management/falsifying accounts, etc... there is really no justification to sell. 


The management subsequently released a long list of initiatives, probably meant to calm investors. Centralized kitchens, tablet ordering at zi char stalls, customer rewards programme, own brand of coffee/tea, etc... pushing on with their growth strategies. They are all good, but action speaks louder than words - It all depends if they can execute and show results now. 

On the good news side, we distributed $1200+ dividends in Q4 for a record-breaking year!


Operating Highlights - Income
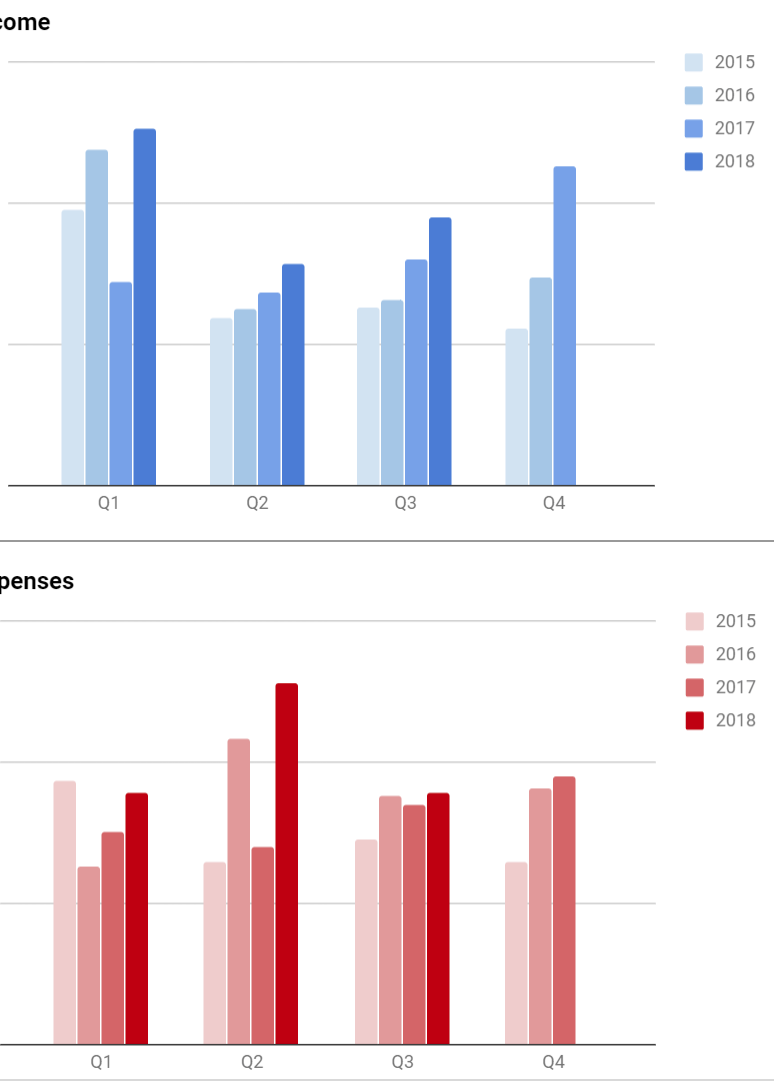
We reached new heights once again, attaining almost 10% higher income than last year - driven by higher base salary (same bonus multiple) and passive income. SG Bonus and IPPT Pass with Incentive were the icing on the cake.


Operating Highlights - Expenses
No special one-time expenses aside from usual Tax and new Insurance payments.

Regular expenses were slightly higher due to several items: Renewal of Stocks Cafe membership for 7 years, health checkup package, and a new pair of Creative Gigawork speakers (could not resist the 12/12 deals).


Utilities cost will increase significantly going forward due to higher recontract mobile and fibre plans. 


Acquisitions & Developments
We traded Capitamall Trust one more time to earn some loose change ($600+), and also fire a bullet on STI after the recent drawdown .This is the closest STI has been to 3000 for more than a year, and valuations are definitely on the cheaper side. Not dirt cheap yet, but a fair price to pay.

As of now, we are most concerned with Singtel and Kimly, and will be monitoring them closely.


Operating Updates
All good times must come to an end - Citibank finally caved in to the raising SIBOR and admended the terms of Maxigain account (from 80% of SIBOR to 70%).

Despite this, calculation shows that we am still able to get at least 2.3% interest (compounded) which makes it competitive against other products and even SSB. 

Good for you Citibank, but do not take it too far. 


Outlook
More in the annual report.

Saturday, November 24, 2018

The 7th Greenland

Back to Greenlands again, for the 7th time.

At first I thought it would serve as an "escape" for me, but once again I am proven wrong.

In the end, I reached the same conclusion as 10 years ago.

I really don't like this environment.

And I did the most WTF thing ever and probably pushing myself to the limits.

In an insomnia state, went to take a 2nd consecutive physical fitness test midway digging a grave.

And I still managed to pass! Even I am surprised.

Also, I reached the conclusion that my Insomnia is definitely not due to work, because it happens even when I'm in this place.

Saturday, October 13, 2018

Why Long Term Investing Works - Explained By Visual

This could be one of the most insightful set of visuals.


If Millennials are planning for retirement 30-40 years from now, they should know the stock market has never cut a loss over any 20-year period from 1926–2015.


The odds of realizing a positive stock return are 100% over any 20-year period during that timeframe. Let me repeat. Stocks have never seen a loss over any 20-year time period from 1926-2015. Never. Not once.


But what about over shorter intervals, you ask? How about 10 years? A sobering 94% of the time there was a gain. 5 years? 86%.


What if you buy today and hope to sell it for a profit next week? Your chances are barely  better than a coin flip.

Saturday, October 06, 2018

Letter To Shareholders (12) - Performance Review 2018Q3

Economy Commentary
Singapore market went through a mini rollercoaster ride in the past 3 months, going up to 3300 then down to 3100 and now back to 3200 again. Trade war seems to have no impact on the US markets as they kept breaking all time high.

From this quarter onwards, we will be discontinuing Quarterly Results Review - it seems to have became a "for the sake of writing" commentary providing only basic information without much substance. Instead, we shall integrate important portfolio developments in the Quarterly Performance Review.


Performance Review Highlights
Our portfolio was saved by the buyout offer of M1 shares (on the last day of Q3!), raising its value nearly 30% in a single day. Entire portfolio value skyrocketed $3700, which I believe is the largest ever single day increase.

We are down 4% year to date compare to 1% down of the STI, mostly dragged down by Kimly. Excluding this stock, we would be nearly even. Would our growth assessment of this coffee shop business come true? Or will this huge position left a huge scar in our portfolio? Only time will tell and 2019 should be a game changing year.

We gave out $2600 worth of dividends (thanks to a massive distribution from Singtel) which is once again our best Q3 yet. This will be a record-breaking year of dividends!


Operating Highlights - Income
Another all-time high quarter - Higher salary, higher passive income and even higher one-time income due to a recontract of mobile plan and selling iPhone for $560 profits. Unfortunately, the expiry of our old corporate plan also meant a much higher monthly recurring cost.

This was a big mistake on hindsight. I did not do enough research before re-contracting, and in the aftermath realized there were much cheaper SIM only plans with huge data, and cost only like $30 in the market. Instead, what I got was a $60 plan with upfront $560 "profits" to spread out the cost.

All in all, it wasn't worth it. I was tricked into believing:
1. My corporate plan discount was higher than what was advertised (turned out the promotion expired like 3 days before I recontract) I did not re-confirmed the discount rate again when I signed.
2. False advertising by a very enthusiastic Citibank Credit Card salesguy, mislead me into believing the benefits are good when there are many terms and clauses making it difficult to hit the advertised rebate rate (common trick by many banks. Haiz. I should have been more aware.)

This mistake is probably going to cost me hundred dollars or so, and lesser data/month for the next 2 years. I really learnt my lesson from this. Always double check! 


Operating Highlights - Expenses
Recurring expenses/one-time expenses were both in-line with the past 3 years, with the traditional August angbao for Mum.


Acquisitions & Developments
We brought Kimly early this quarter based on the same proposition: 

Kimly - Defensive consumer staple with strong cash flow, high cash balance and organic growth prospects. This is more of a capital-gain and opportune play.

We sold Capitamall Trust to earn some "coffee money". Hopefully we will get a chance to buy it back soon (afternote: we did), as Funan should provide some catalyst for the longer term. We are not so sure about the Westgate acquistion.


Operating Updates
Finally decided to do a little streamlining by closing our OCBC360 account. The $3000 could be better off earning $5/mth in DBS Multiplier compared to $0.70 per month in OCBC360.

We delayed so long mainly due to GIRO and other stock crediting arrangements, but now I realize it's not that difficult to switch. Everything can be done online and essentially a new submission will overwrite the previous. This will also reduce the hassle of transferring small amounts here and there just to pay different bills every month.

With that, we officialy say goodbye to OCBC360 which has accompanied us for more than 5 yrs.


Outlook
My working capital remains lean, with about 3 bullets (1.5 bullet from the recent sale of CMT)  to play around with. We intend to selectively "trade" using what we have right now while waiting for the big refill in December to come in. The future of Kimly will make or break our portfolio this year.

2018 is shaping up to be another milestone year as we break major goals: "25 years expense" holy grail, 5 digits passive income and more. Looking forward to the annual report!

Some stocks on our watchlist include:

STI ES3 (3.2), ST Engineering (3.2), Capitaland (2.8), Sembcorp Ind (2.5 or 75% of book value), Mapletree Commercial Trust (1.55), Singtel (3), Raffles Medical Group (0.9), Far East HTrust (0.6 or 6.5% yield), Frasers Property (Below 1.6, NAV at 2.45, 8.6c dividend over 5% yield)

What Everybody Is Getting Wrong About FIRE

Another classic MMM article that will go down in history.

Strong valid points and rebuttal against all the FIRE-nayers, either because they are ignorant/misunderstood about what FIRE truly stands for, or they have a psychological problem of financial fear.

No matter how you look at it, FIRE can only be a good thing.

FIRE is not about early retirement.

FIRE is about giving you the freedom to be the happiest person you can possibly be.

When I see celebrities with 20M networth criticizing FIRE, they will probably say the same thing when they reach 200M networth.

How much is enough? Until the day you die?

Once again, nay-sayers are entertainment at best.

MMM is the real deal.